Business Valuation Models: A Complete Guide to Methods, Formulas, and Applications
Business valuation models are essential financial tools used to estimate the economic value of a company.
Investors, business owners, financial analysts, and corporate decision-makers rely on these models to evaluate investment opportunities, negotiate acquisitions, assess fundraising proposals, and make strategic financial decisions.
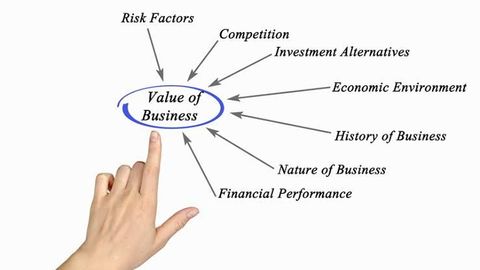
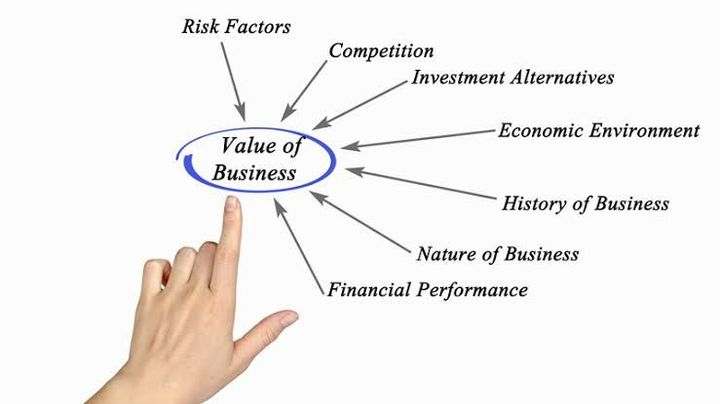
Determining the value of a business involves more than examining its revenue or profit. A company's valuation may depend on its future cash flows, growth potential, assets, liabilities, competitive position, industry conditions, and exposure to financial risks.
Different valuation models approach this process from different perspectives. Some estimate value based on future cash flows, while others compare a company with similar businesses or examine the value of its underlying assets.
Understanding these approaches helps investors and business professionals select appropriate valuation methods, interpret financial information, and make better-informed decisions.
What Are Business Valuation Models?
Business valuation models are analytical frameworks used to estimate the economic value of a company or its ownership interests.
These models combine financial information, market data, assumptions, and mathematical calculations to produce an estimated value.
Other adjustments may be required for items such as minority interests, preferred shares, and nonoperating assets.
A valuation may be required for several purposes, including:
Mergers and acquisitions
Investment analysis and fundraising
Business sales and ownership transfers
Financial reporting
Strategic planning
Shareholder disputes and certain legal matters
Tax and estate planning, where applicable
The appropriate valuation model depends on the company's business model, financial performance, available information, and the purpose of the valuation.
For example, a mature company with stable cash flows may be suitable for a discounted cash flow analysis. A publicly traded company may be evaluated using comparable company multiples, while a property-holding business may require a detailed assessment of its underlying assets.
No single valuation model is universally appropriate for every company.
Why Business Valuation Is Important
Business valuation provides a structured basis for understanding a company's financial worth and evaluating potential decisions.
1. Supporting Investment Decisions
Investors use valuation models to compare a company's estimated value with its current market price or proposed investment price.
If the estimated value differs significantly from the price being offered, investors may investigate whether the difference reflects an opportunity, unrealistic assumptions, or risks that the model has not fully captured.
2. Facilitating Mergers and Acquisitions
During an acquisition, both buyers and sellers need a basis for negotiating a transaction price.
Buyers may assess future cash flows, potential synergies, and integration costs. Sellers may emphasize earnings potential, competitive advantages, and the strategic value of the business.
Valuation models help structure these discussions, although the final transaction price also depends on negotiations and deal conditions.
3. Measuring Business Performance
Valuation analysis can reveal how growth, profitability, operating margins, and capital requirements influence company value.
Management can use these insights to evaluate strategic initiatives and understand which factors contribute most to long-term financial performance.
4. Supporting Fundraising
Businesses seeking investment may need to estimate their value before issuing shares or negotiating ownership terms.
Valuation helps establish a starting point for discussions between founders and potential investors. For early-stage companies, however, uncertainty about future performance can make estimates particularly sensitive to assumptions.
Major Types of Business Valuation Models
Several valuation methods are commonly used in financial analysis. Each has strengths and limitations, so analysts often use multiple approaches to develop a more complete assessment.
1. Discounted Cash Flow Model
The discounted cash flow model, commonly known as DCF, estimates a company's value based on the present value of its expected future cash flows.
The underlying principle is that money received in the future is worth less than money received today because of the time value of money and the risks associated with future outcomes.
A DCF model typically involves forecasting future cash flows, selecting an appropriate discount rate, estimating terminal value, and calculating the present value of these amounts.
When forecasting free cash flow to the firm, analysts commonly use the weighted average cost of capital, or WACC, as the discount rate.
Terminal value represents the estimated value of cash flows beyond the explicit forecast period.
Advantages of the DCF Model
DCF connects valuation to a company's expected cash-generating ability. It allows analysts to incorporate assumptions about revenue growth, operating margins, capital expenditure, and working capital.
It is especially useful when a company has reasonably predictable cash flows.
Limitations of the DCF Model
DCF results can change substantially when analysts adjust the discount rate, growth assumptions, or terminal value.
Forecasting future cash flows is difficult for businesses with volatile earnings, uncertain market conditions, or limited operating histories.
2. Comparable Company Analysis
Comparable company analysis estimates a business's value by examining how similar companies are valued in the market.
Analysts identify comparable businesses and calculate financial valuation multiples based on metrics such as revenue, EBITDA, or earnings.
Common multiples include:
Enterprise value to EBITDA
Enterprise value to revenue
Price-to-earnings ratio
Price-to-book ratio, where relevant
For example, suppose comparable companies trade at an average enterprise value-to-EBITDA multiple of 8 times. If the company being valued generates EBITDA of $10 million, applying that multiple produces an illustrative enterprise value of $80 million.
This estimate is only as reliable as the comparability of the companies and the quality of the selected financial data.
Advantages of Comparable Company Analysis
This method reflects current market pricing and is relatively straightforward to communicate.
It can be particularly useful for publicly traded companies and businesses operating in industries with sufficient comparable companies.
Limitations of Comparable Company Analysis
Companies may differ in growth prospects, profitability, leverage, size, geography, and risk.
Market conditions can also cause comparable-company multiples to rise or fall, meaning that market pricing may not always reflect a company's long-term economic potential.
3. Precedent Transaction Analysis
Precedent transaction analysis estimates a company's value by examining prices paid in previous acquisitions of comparable businesses.
Analysts review transaction values and financial metrics to determine relevant valuation multiples.
For example, if similar businesses were acquired at enterprise values averaging 9 times EBITDA, that multiple may provide a starting point for evaluating another company in the same industry.
However, acquisition prices may include control premiums, expected synergies, or strategic benefits that are not available to every buyer.
Advantages of Precedent Transaction Analysis
The method is based on actual transaction prices rather than only publicly traded market valuations.
It can be useful during mergers, acquisitions, and negotiations involving the sale of a business.
Limitations of Precedent Transaction Analysis
Relevant transactions may be limited or difficult to compare. Differences in market conditions, deal structures, and buyer motivations can also affect valuation multiples.
4. Asset-Based Valuation Model
Asset-based valuation estimates a company's value by assessing its assets and liabilities.
The basic net asset formula is:
For valuation purposes, assets and liabilities may need to be adjusted to reflect their current economic values rather than their accounting book values.
This approach may be appropriate for holding companies, investment entities, asset-intensive businesses, or companies undergoing liquidation.
Advantages of Asset-Based Valuation
The model provides a direct framework for assessing tangible assets, financial investments, property, and liabilities.
It can be especially relevant when the value of a company's underlying assets is more important than its future operating cash flows.
Limitations of Asset-Based Valuation
The approach may undervalue businesses whose economic value depends heavily on intangible assets, intellectual property, customer relationships, brand strength, or future earnings potential.
It may also be unsuitable as a standalone method for profitable service businesses with relatively few tangible assets.
5. Dividend Discount Model
The dividend discount model estimates the value of a company's equity by discounting its expected future dividends.
It is most applicable to companies with established dividend policies and reasonably predictable dividend growth.
A common version is the Gordon growth model:
Where:
\(P_0\) = estimated current share value
\(D_1\) = expected dividend per share in the next period
\(r_e\) = required return on equity
\(g\) = expected perpetual dividend growth rate
The model requires the expected growth rate to remain below the required return on equity.
Advantages of the Dividend Discount Model
The model focuses directly on the cash distributions shareholders expect to receive.
It can be useful for mature companies with stable dividend policies.
Limitations of the Dividend Discount Model
It is less suitable for companies that do not pay dividends or whose dividend policies are highly unpredictable.
Small changes in long-term growth assumptions can also significantly affect the estimated value.
6. Earnings-Based Valuation
Earnings-based valuation uses a company's earnings to estimate its value, often through an earnings multiple.
For example, an analyst may apply a price-to-earnings multiple to normalized net income or use an enterprise value multiple based on EBITDA.
This approach is common because earnings measures are widely used in investment analysis.
However, reported earnings may be affected by unusual expenses, accounting choices, nonrecurring gains, and differences in capital structure.
Analysts should therefore evaluate the quality and sustainability of earnings before applying a multiple.
Enterprise Value vs. Equity Value
Understanding the distinction between enterprise value and equity value is essential when using business valuation models.
Enterprise value generally represents the value of a company's operating business attributable to both debt and equity capital providers.
Equity value represents the value attributable to shareholders after accounting for debt and other relevant claims, subject to the specific valuation framework.
A simplified reconciliation is:
For example, a business may have an enterprise value of $100 million, cash of $10 million, and debt of $30 million. Under the simplified formula, its equity value would be $80 million.
Analysts must use consistent definitions. An enterprise value multiple should generally be applied to an operating metric such as EBITDA, while an equity value multiple is typically applied to an equity-level metric such as net income.
How to Choose the Right Business Valuation Model
Selecting a valuation model requires consideration of the company's financial characteristics and the purpose of the analysis.
Evaluate the Company's Stage of Development
Established businesses with predictable cash flows may be suitable for DCF analysis.
Early-stage companies with limited operating histories may require a combination of scenario-based financial forecasts, comparable-company analysis, and transaction benchmarks.
Consider Industry Characteristics
Different industries have different operating models and valuation conventions.
For example, financial institutions are often analyzed using equity-based metrics and industry-specific approaches, while industrial companies may be assessed using EBITDA multiples and DCF models.
Assess Data Availability
The quality of a valuation depends on the reliability of the information available.
A company with detailed historical financial statements and credible forecasts may support a more rigorous DCF model than a business with limited financial records.
Use Multiple Methods
Where practical, analysts should compare results from several valuation approaches.
If a DCF model produces a significantly different result from comparable-company analysis, the difference may reveal assumptions that require further investigation.
Using multiple methods does not automatically improve accuracy, but it can help identify inconsistencies and make the final estimate more robust.
Common Mistakes in Business Valuation
Business valuation models can produce misleading results when analysts use unrealistic assumptions or inconsistent financial measures.
One common mistake is overestimating future revenue growth without considering competition, customer demand, and operating capacity.
Another is selecting an inappropriate discount rate or applying valuation multiples from companies with significantly different business risks.
Analysts may also overlook debt obligations, working capital requirements, capital expenditure, and nonrecurring financial items.
Terminal value can become another source of error in DCF analysis, particularly when it represents a large proportion of the total estimated value.
Finally, valuation estimates should not be treated as guaranteed transaction prices. The amount a buyer is willing to pay may depend on strategic objectives, financing conditions, negotiation strength, and deal-specific risks.
The Role of Financial Modeling and Technology
Financial modeling software and analytics platforms have made business valuation more efficient and transparent.
Spreadsheets allow analysts to build DCF models, calculate valuation multiples, conduct sensitivity analysis, and compare different scenarios.
More advanced financial systems can integrate accounting data, market information, business forecasts, and industry benchmarks into a consistent analytical workflow.
Artificial intelligence can assist with data extraction, financial statement analysis, and the identification of comparable businesses. However, AI-generated estimates should be reviewed for data quality, calculation errors, inconsistent definitions, and unsupported assumptions.
Technology can improve the speed of valuation analysis, but the quality of the final result still depends on sound financial judgment and reliable inputs.
Future Trends in Business Valuation
Business valuation continues to evolve as financial markets, technology, and corporate business models change.
Data analytics is improving how analysts evaluate company performance, compare businesses, and test financial assumptions.
Scenario modeling is also becoming increasingly important as organizations face uncertainty related to interest rates, economic growth, competition, and technological change.
Intangible assets, including intellectual property, software, customer relationships, and brand value, remain important considerations, particularly for technology-driven businesses.
At the same time, investors and financial professionals are paying greater attention to business resilience, cash generation, governance, and the sustainability of growth.
These developments reinforce the importance of combining quantitative valuation models with a thorough understanding of the business and its operating environment.
Conclusion
Business valuation models provide a structured way to estimate company value and support decisions involving investments, acquisitions, fundraising, and strategic planning.
The discounted cash flow model focuses on future cash generation, comparable company analysis uses market multiples, precedent transaction analysis examines acquisition prices, and asset-based valuation evaluates net assets. Dividend discount and earnings-based methods offer additional approaches for suitable businesses.
Each model has strengths and limitations, and the reliability of any estimate depends on the quality of its assumptions, financial information, and market comparisons.